NABKISAN’s Social Bond: Why a Credit Rating and a Social-Purpose Label Mean Different Things
By: admin
News & Insights
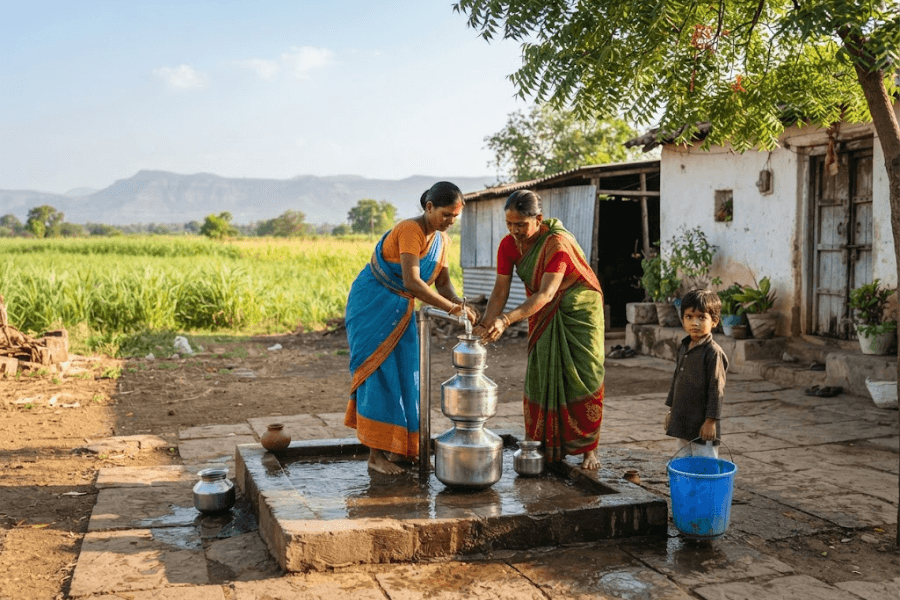
NABKISAN’s Social Bond: Why a Credit Rating and a Social-Purpose Label Mean Different Things
Debt instruments are usually evaluated through questions about repayment capacity, interest obligations, maturity and risk.
But some debt instruments introduce another dimension: the purpose for which the money will be used.
NABKISAN Finance Limited's ₹180 crore Water, Sanitation and Hygiene (WASH) social bond, listed on the National Stock Exchange on 1 October 2026, provides a useful example.
The five-year instrument carries an annual coupon of 8.10%, matures in September 2031 and has received CRISIL AAA (Stable) and CARE AAA (Stable) ratings. The issue was oversubscribed 1.8 times.
The proceeds are intended to support access to safe water, sanitation and hygiene solutions in rural and underserved communities.
The transaction brings together two distinct considerations in debt markets:
The credit risk associated with the issuer or instrument, and the purpose for which the funds are raised.
Understanding the difference is important for companies planning to raise debt and for anyone evaluating such instruments.
What makes a social bond different?
A conventional bond allows an issuer to raise money from investors in return for meeting the instrument's contractual obligations.
A social bond adds a defined social purpose to the use of the proceeds.
In NABKISAN's case, the proceeds are earmarked for WASH-related initiatives intended to expand access to water, sanitation and hygiene solutions.
This gives the financing a specific purpose beyond general corporate funding.
For an issuer, such a structure can connect its borrowing programme with an identified social objective.
For investors, it provides information about the intended use of the funds.
However, the social purpose of a bond does not, by itself, establish the issuer's ability to repay it.
That requires a separate assessment.
Why the credit rating still matters
NABKISAN's bond carries AAA (Stable) ratings from CRISIL and CARE Ratings.
A credit rating represents the respective agency's assessment of credit risk under its methodology and based on the information available to it.
It is not a guarantee of repayment, and it does not independently verify that the financed activities will achieve every intended social outcome.
This distinction is fundamental.
The social designation concerns the purpose of the financing. The credit rating concerns the agency's assessment of credit risk.
A bond may have a clearly defined social purpose, but investors still need to understand the creditworthiness of the issuer and the terms of the instrument.
Similarly, a highly rated bond's credit assessment should not be confused with an independent measurement of its social impact.
The difference between the use of proceeds and repayment capacity
Consider two hypothetical issuers raising money for water infrastructure.
The first has a defined programme for deploying the funds but limited financial flexibility and substantial near-term debt maturities.
The second has a comparable social objective but a different financial structure, with stronger liquidity and a more manageable debt-servicing profile.
The social purpose alone does not determine which issuer presents the lower credit risk.
An independent credit assessment must consider the relevant financial and business factors.
Depending on the issuer and instrument, these can include cash-flow generation, leverage, liquidity, debt maturity, funding access, governance and the structure of the obligations.
The use of proceeds is important, but it does not replace the underlying credit analysis.
What the NABKISAN transaction demonstrates
NABKISAN's bond combines a five-year maturity with a specified WASH-related purpose and AAA (Stable) ratings from two agencies.
The issue also attracted bids equivalent to 1.8 times the amount being raised.
These are useful facts about the transaction, but they should be interpreted carefully.
Oversubscription indicates that investor bids exceeded the issue size. It does not establish that all similar social bonds will receive comparable demand.
Likewise, the coupon rate is a feature of this particular instrument. It should not be treated as a universal benchmark for the cost of social-bond financing.
The broader lesson is that debt-market transactions should be evaluated on their individual terms, credit characteristics and funding objectives.
What companies should consider before issuing purpose-linked debt
For companies exploring social or other purpose-linked debt instruments, several questions deserve attention.
1. Is the use of proceeds clearly defined?
The issuer should be able to explain the activities or projects the funds are intended to support.
The scope should be sufficiently clear to distinguish the proposed use from unrestricted general corporate funding.
2. Can the issuer demonstrate how the proceeds will be used?
Companies should consider what internal processes, documentation and reporting arrangements are needed to track the deployment of funds in accordance with the applicable framework.
The exact requirements depend on the instrument and relevant regulations or market standards.
3. What is the underlying credit profile?
The company's ability to meet its financial obligations remains a separate consideration.
Management should understand its leverage, liquidity, cash flows, repayment schedule and future funding needs.
4. Does the maturity fit the funding requirement?
Debt tenure should be evaluated against the nature of the expenditure, the expected cash-flow profile and the issuer's other obligations.
A mismatch between the timing of cash inflows and repayments can create refinancing pressure even when the funded activity has a clear social objective.
5. How will the company communicate the financial and social dimensions?
Investors should be able to distinguish the financial obligations of the instrument from its stated purpose and any associated reporting commitments.
Clear documentation can help prevent confusion between credit risk and impact-related claims.
Is a social bond automatically cheaper?
No.
The label alone does not establish that an issuer will obtain a lower borrowing cost.
The pricing of a debt instrument can depend on the issuer's credit profile, prevailing interest rates, liquidity, tenure, security, market demand and the specific terms of the issue.
A social designation may be relevant to investors with particular mandates, but the financing outcome depends on the transaction and the market in which it is issued.
Companies should therefore evaluate the overall economics and requirements of the instrument rather than assuming that a particular label will result in a funding advantage.
Why this matters for credit rating preparedness
A company planning to issue debt needs to understand both its funding objective and its ability to service the proposed obligations.
That preparation should include a clear view of the intended use of proceeds, the resulting liability structure, the company's existing borrowings and its projected cash flows.
Where a bond carries additional purpose-related commitments, management should also understand the associated documentation and reporting expectations.
These considerations help build a clearer picture of the transaction before the company approaches the market or begins a rating exercise.
The rating itself remains the independent decision of the registered credit rating agency.
Conclusion
NABKISAN's ₹180 crore WASH social bond provides a timely example of how debt financing can be linked to a defined social objective.
It also illustrates an important distinction for issuers and investors.
A bond's purpose and its credit risk are separate questions, even when they form part of the same transaction.
For companies considering purpose-linked debt, the starting point should be a clear funding plan, a well-understood capital structure and a realistic assessment of debt-servicing capacity.
The social objective explains what the money is intended to support.
The credit assessment addresses the financial risk associated with the instrument.
Both matter, but neither should be treated as a substitute for the other.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial, investment, legal or credit-rating advice. Credit ratings are assigned independently by SEBI-registered Credit Rating Agencies under their respective methodologies. A credit rating is not a guarantee of repayment or social impact. FinMen Advisors provides preparatory and advisory support to companies undergoing a rating exercise and does not issue, influence or guarantee any rating outcome.