ACME Solar’s Outlook Revised to Positive: What an Outlook Change Means for Credit Quality
By: admin
News & Insights
ACME Solar’s Outlook Revised to Positive: What an Outlook Change Means for Credit Quality
A credit rating is not only about the rating symbol attached to a company.
The outlook can provide an important indication of how a rating agency currently views the direction of a company's credit profile.
A recent rating action on ACME Solar Holdings Limited provides a useful example.
CRISIL Ratings has reaffirmed ACME Solar Holdings' long-term rating at AA- and revised the outlook from Stable to Positive. The action reflects expectations of an improvement in the company's financial risk profile, supported by deleveraging and stronger cash-flow generation as its projects are commissioned.
The distinction between the rating and the outlook is important.
The rating has remained unchanged at AA-. What has changed is the agency's assessment of the potential direction of the credit profile.
For businesses and finance teams, understanding this distinction can provide useful insight into how rating actions work.
Rating versus outlook: what is the difference?
A credit rating represents a rating agency's assessment of the credit quality of a rated instrument or issuer under its applicable methodology.
The outlook, on the other hand, provides an indication of the potential direction of the rating over a defined period based on the agency's current expectations.
A Positive outlook does not mean that a rating upgrade is guaranteed.
Similarly, a Stable outlook does not mean that a rating can never change.
The eventual rating action depends on how the company's financial and business profile develops and how that compares with the rating agency's expectations and criteria.
In ACME Solar's case, the rating remains AA-, while the outlook has moved to Positive.
That makes the development particularly useful for understanding how changes in financial risk can precede an actual rating action.
Why did the outlook change?
According to CRISIL, the positive outlook reflects an expected improvement in ACME Solar's financial risk profile.
The key factors include deleveraging and stronger cash-flow generation, supported by the commissioning of projects.
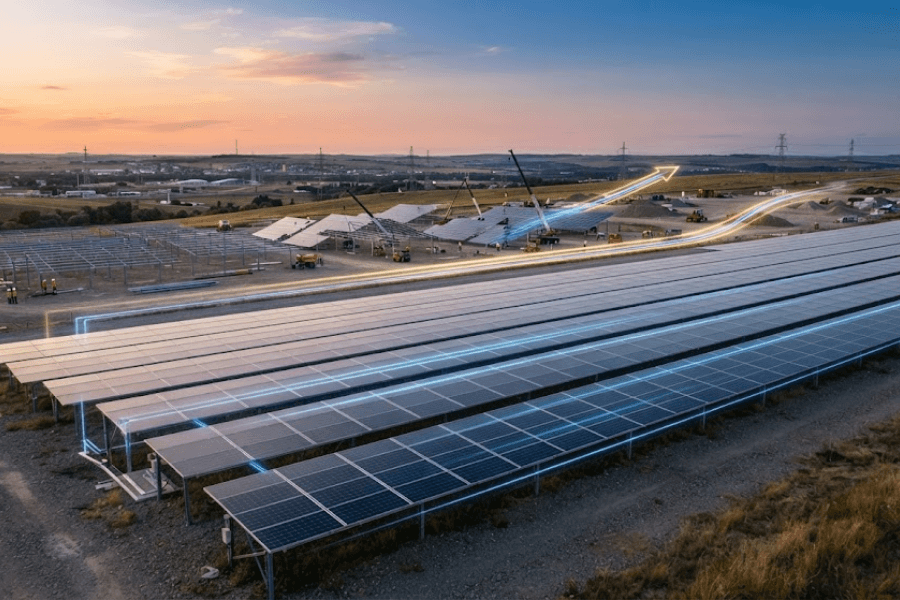
For a renewable energy platform, project commissioning can be particularly important because projects move from the construction phase towards operating assets capable of generating recurring cash flows.
As projects become operational, the company's ability to generate cash and service its financial obligations can change.
That does not mean that project commissioning automatically results in stronger credit quality.
The credit implications depend on factors such as project performance, debt levels, cash-flow generation, liquidity and the company's ability to manage its obligations.
Why deleveraging matters
Debt is an important part of the capital structure of infrastructure and renewable energy businesses.
Projects often require significant upfront investment and may therefore involve substantial borrowing during development and construction.
As operating assets begin generating cash flows, the financial profile can evolve.
If debt reduces relative to the company's ability to generate cash, leverage can moderate.
This can provide greater financial flexibility and reduce pressure on debt-servicing capacity.
For credit analysis, the direction of leverage can therefore be as important as its current level.
A company moving from a highly leveraged construction phase towards a more stable operating phase may gradually develop a different financial risk profile.
Cash-flow generation is equally important
Deleveraging is only one part of the equation.
The ability of a business to generate sustainable cash flows is fundamental to its capacity to service debt.
For renewable energy companies, this requires consideration of factors such as:
Project commissioning
Generation performance
Power sale arrangements
Receivables
Operating costs
Debt servicing
Liquidity
Counterparty quality
A project may have strong long-term economics, but the timing and predictability of cash flows remain important from a credit perspective.
This is why rating assessments look beyond headline revenue or installed capacity.
What does a Positive outlook actually mean for a company?
A Positive outlook should be interpreted carefully.
It indicates that, based on the rating agency's current assessment, there is potential for the credit profile to strengthen sufficiently to support a higher rating in the future.
But the future action depends on actual performance.
For management teams, this creates an important distinction:
An improving credit profile is demonstrated through financial and operating performance. It is not created simply by receiving a Positive outlook.
Businesses should therefore focus on the underlying drivers that influence credit quality.
These can include:
Leverage
How much debt does the company carry relative to its earnings and cash flows?
Debt servicing
Can operating cash flows comfortably support interest and principal obligations?
Liquidity
Does the company have adequate liquidity to manage near-term requirements and unexpected pressure?
Project execution
Are projects being commissioned as planned and within expected cost and timelines?
Cash-flow visibility
How predictable are the company's future cash flows?
Business risk
What external factors could affect generation, tariffs, counterparties or operating performance?
The broader lesson for companies preparing for a rating
The ACME Solar action illustrates an important point for companies approaching a credit rating exercise.
Rating agencies do not look only at the company's current financial position.
They also assess the direction and sustainability of that position.
A company may therefore need to demonstrate not only where its leverage stands today, but also how its financial profile is expected to evolve.
For businesses investing heavily in expansion, this becomes particularly relevant.
A company may initially take on significant debt to fund growth. The credit assessment then needs to consider whether the resulting assets will generate sufficient and sustainable cash flows to support that debt.
The quality of the transition from investment to operating cash flow can therefore become a critical part of the credit story.
What should management monitor?
Companies looking to strengthen their credit profile should maintain a clear view of the factors that drive credit assessment.
A practical review can include:
1. Debt trajectory
Is absolute debt increasing or decreasing?
More importantly, is debt declining relative to the company's earnings and cash-generation capacity?
2. Cash-flow trajectory
Are operating cash flows becoming more predictable and sufficient to meet financial obligations?
3. Project execution
Are new projects being commissioned on schedule and within planned budgets?
4. Liquidity
Can the company meet its near-term obligations without relying excessively on refinancing?
5. Financial flexibility
Does the company have sufficient headroom to absorb unexpected operating or market pressures?
6. Business risk
Are there sector-specific risks that could materially affect the company's cash flows or financial position?
These factors provide management with a more useful framework than focusing on the rating symbol alone.
Why the outlook change matters beyond ACME Solar
The ACME Solar development also demonstrates how credit assessments can evolve as a company's business and financial profile changes.
A company can remain at the same rating level while the outlook changes because the rating agency sees a different trajectory emerging.
That is why management teams should monitor rating factors continuously rather than treating a rating exercise as a one-time event.
The objective should be to understand:
What supports the current rating?
What could put pressure on it?
What financial or operating changes could alter the credit profile?
This becomes particularly important for businesses with large project pipelines, significant debt-funded expansion or changing cash-flow profiles.
The FinMen perspective
For businesses preparing for a credit rating exercise, understanding the factors behind the rating is as important as understanding the rating itself.
At FinMen Advisors, our focus is Credit Rating Advisory.
We support businesses in preparing for the credit-rating process by helping management assess relevant business and financial factors, organise the required information and prepare for engagement with the rating agency.
The credit rating itself is assigned independently by the relevant SEBI-registered Credit Rating Agency.
A Positive outlook should therefore not be interpreted as a guaranteed upgrade, just as a Stable outlook should not be treated as a permanent rating position.
The more useful approach is to understand the underlying credit drivers and how the company's financial profile is evolving.
Preparing for a credit rating exercise?
Understand the factors shaping your credit profile before the rating conversation begins.
FinMen Advisors
Credit Rating Advisory
Disclaimer
This article is for general informational and educational purposes only and does not constitute financial, investment, credit or legal advice. The discussion is based on publicly available information, including CRISIL Ratings' published rating action on ACME Solar Holdings Limited. Credit ratings and outlooks are independent opinions of the relevant Credit Rating Agency and may change based on subsequent information and circumstances. FinMen Advisors provides Credit Rating Advisory services and does not issue credit ratings or guarantee any rating outcome.